
Two siblings inherit a flat in Hyderabad. One lives in London, the other in Bengaluru. When they decide to sell fifteen years later, the buyer’s CA returns with a problem: different tax deduction rates apply to each seller, requiring two separate filings. The NRI sibling needs to be physically present in India or produce a registered Power of Attorney. Repatriation can only happen for the NRI’s half of the proceeds. And if the buyer calculates the deductions incorrectly, the buyer becomes personally liable for the shortfall.
None of this was complicated when they both lived in India. The rules did not change; the circumstances did.
Joint ownership of property in India is common. What most co-owners do not think through is how it works when one of them becomes non-resident.
What Joint Ownership Actually Means
Most sale deeds in India name two or more owners without specifying the legal nature of the joint ownership. Under the Transfer of Property Act, the two recognised forms are joint tenancy (with a right of survivorship) and tenancy in common (where each owner holds a defined, separable share that can be independently inherited or transferred).
In practice, Indian courts treat co-ownership as tenancy in common in nearly all cases. Joint tenancy with survivorship is essentially unknown outside HUF coparcenary, and courts have been reluctant to recognise it even where a deed attempts to create one. If a co-owner dies, their share does not pass automatically to the other owner. It passes to their legal heirs.
The share each co-owner holds determines what they can repatriate when the property is sold, what tax rate applies to their proceeds, and what happens to their portion when they die. If the deed does not specify the share, which is common in older deeds, courts presume equal shares.
FEMA and Repatriation: Only Your Share
FEMA permits NRIs and OCIs to jointly own property in India with resident Indians, provided the property was acquired through a permitted route. Permitted routes include: purchase using NRE or NRO account funds or foreign remittances, inheritance, and gift from a relative. NRIs cannot acquire agricultural land, plantation property, or farmhouses through purchase, regardless of the ownership structure.
When the jointly owned property is sold, the repatriation rules apply only to the NRI’s proportionate share of the proceeds. If the NRI owns half of a property sold for Rs 1 crore, Rs 50 lakh is the maximum amount they can remit abroad, subject to the overall cap of USD 1 million per financial year from the NRO account.
The resident co-owner’s share stays in India. The NRI cannot pool the full Rs 1 crore into their NRO account and repatriate it. The resident receives their share in their Indian bank account, and that is where it stays. Routing the resident’s share through the NRI’s NRO account for repatriation is a FEMA violation.
This matters especially for inherited property where the original purchase was made with Indian funds. The RBI permits repatriation from NRO even in these cases, but the USD 1 million annual cap applies across all NRO remittances that year. If the NRI’s share is large, repatriation may need to be spread across multiple financial years.
TDS on Joint Sales: Two Sellers, Two Rates
When a resident Indian sells property worth more than Rs 50 lakh, the buyer deducts 1% TDS under Section 194IA of the Income Tax Act and deposits it with the government.
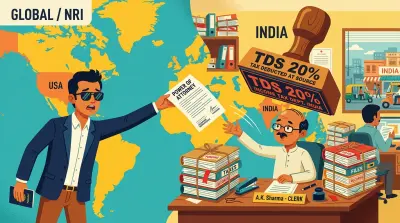
When an NRI sells property, the buyer follows the non-resident withholding entry under Section 393 of the Income-tax Act, 2025 (the successor to former Section 195). The holding period, transfer date, taxable sum, surcharge, cess and any valid certificate can affect the result. Do not treat the 12.5% long-term capital-gains rate as an automatic withholding instruction.
When the sellers are one resident and one NRI, both rules apply in the same transaction. The buyer must split the sale proceeds correctly and apply the right rate to each seller’s share. This requires separate TDS calculations and separate filings. Many buyers, and many buyer-side CAs, are not prepared for this.
The practical consequence is that transactions sometimes stall. Buyers hesitate when they realise the TDS mechanics are more complicated than a standard transaction. Some apply the non-resident rule to the entire sale amount, treating the whole transaction as an NRI sale. This can overtax the resident co-owner and create an excess deduction that must be reconciled later.
The NRI co-owner can apply for a lower-deduction certificate using Form 128 under Section 395(1) before the sale. The certificate specifies the rate the buyer may use based on the estimated tax position. Without it, any excess generally has to be reconciled through the return and refund process.
The lower-deduction certificate guide explains the current Form 128 evidence and timing. If excess tax has already been deducted, the NRI property-sale TDS refund guide covers the recovery route.
Selling: Both Signatures, One Registration
A sale deed must be signed by all co-owners in person before the Sub-Registrar. An NRI who cannot travel to India for the registration must execute a registered Power of Attorney authorising someone else to sign on their behalf.
The POA process involves: drafting the document to specifically authorise the sale of the named property, notarising it in the country of residence, getting it apostilled (for countries that are party to the Hague Apostille Convention, including the UK, USA, Australia, Canada, and most of Europe) or attested by the Indian Embassy or High Commission, and then registering it at the Sub-Registrar’s office in India within three months of execution. The registration must happen in the district where the property is located or where the NRI’s address is recorded in government records.
If the NRI co-owner and the resident co-owner disagree on whether to sell, neither can act unilaterally. The only legal remedy is a partition suit in a civil court asking the court to either physically divide the property (if that is feasible) or order a sale and divide the proceeds. Partition suits move slowly in Indian courts. In the interim, neither owner can sell their share to a third party without the other’s consent, because a buyer acquiring only an undivided interest in a property has very limited practical value.
When a Co-Owner Dies: The Multiplication Problem
Joint tenancy with survivorship - where the surviving co-owner automatically inherits the other’s share - is essentially unknown in Indian property law outside HUF coparcenary arrangements. Indian courts have generally been reluctant to recognise it even when sale deeds attempt to create it. In practice, most jointly held property is treated as tenancy in common regardless of how it is described in the deed.
Under tenancy in common, which covers most jointly held property in India, the deceased co-owner’s share passes to their legal heirs. This is where joint ownership can become significantly more complicated for the NRI who survives.
Consider: an NRI co-owns a property with a sibling who is resident in India. The sibling dies without a will and leaves three adult children. The sibling’s half-share now belongs equally to all three children. The NRI now co-owns the property with three people instead of one. All three must agree to any future sale or lease. Each must either appear at registration or issue a registered POA. If any of them are themselves non-resident, the FEMA and TDS complications multiply accordingly.
This situation can arise from a single death and no will. It is not unusual. Intestate succession in India, under the Hindu Succession Act or the applicable personal law, distributes property to a class of heirs simultaneously. A property that was manageable with two co-owners becomes a coordination problem with five or six.
The simplest preventive measure is for both co-owners to execute wills specifying what happens to their respective shares. A will does not prevent disputes, but it reduces the number of unknown heirs and makes the succession process substantially cleaner. The NRI co-owner’s will, if executed abroad, should ideally be notarised and registered in India as well to reduce complications at probate.
For the document choices, see the comparison of a will and succession certificate and the guide to estate planning for Indian property.
Before the Problem Arrives
Joint ownership of Indian property is not inherently problematic. Many NRIs co-own property with family members without any difficulties for years. The complications arise at specific trigger points: when the property is sold, when a co-owner becomes or stops being non-resident, when a co-owner dies, or when co-owners stop agreeing.
The NRIs who handle these moments well are the ones who understood the ownership structure in advance. That means knowing the share split, knowing whether your POA is current and registered, knowing your expected repatriation route, and having a sense of what the succession picture looks like on both sides.
Assetly verifies your ownership status and identifies gaps in your documents - including co-ownership complications - before they become problems. Free to start at assetlyhq.com.